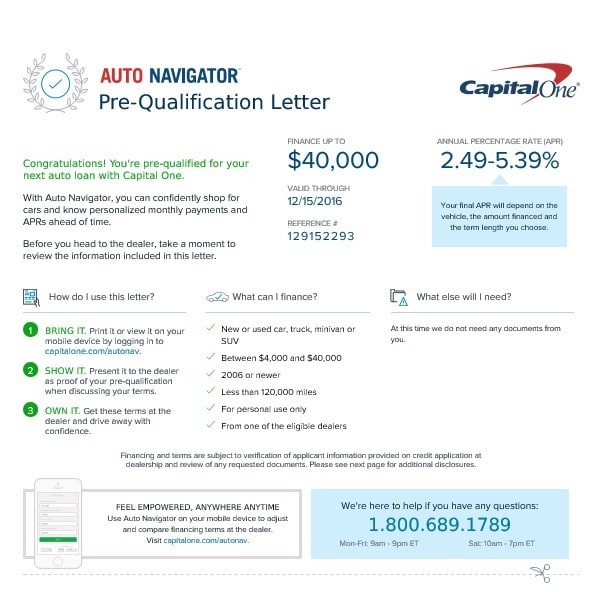
Capital One Auto Loan Pre-Approval Exposed: What Dealers Hide About Your Rate
The Auto Navigator online interface includes an integrated monthly payment estimator that lets shoppers model down payments, trade-in valuations, and term lengths. If the payment structure presented on the final paperwork deviates from the estimator by more than a few dollars, pause the transaction.
Ask the finance manager for the direct lending sheet: "What was Capital One's approved buy rate for my application?"
If the dealer insists the marked-up rate is non-negotiable or refuses to remove dealer-installed add-ons, walking away remains your most effective move. Buyers stuck in high-rate loans also have immediate recourse through auto loan refinance options.
Capital One offers direct refinancing for loans originated by competitors, but they will not refinance their own existing loans. If you complete a transaction financed through Capital One with an inflated dealer markup, apply to an outside credit union or independent online lender within 30 to 90 days. A borrower with clean repayment history can often refinance a marked-up 11% loan down to a competitive 7.5% through an external institution, eliminating the dealer's markup entirely.